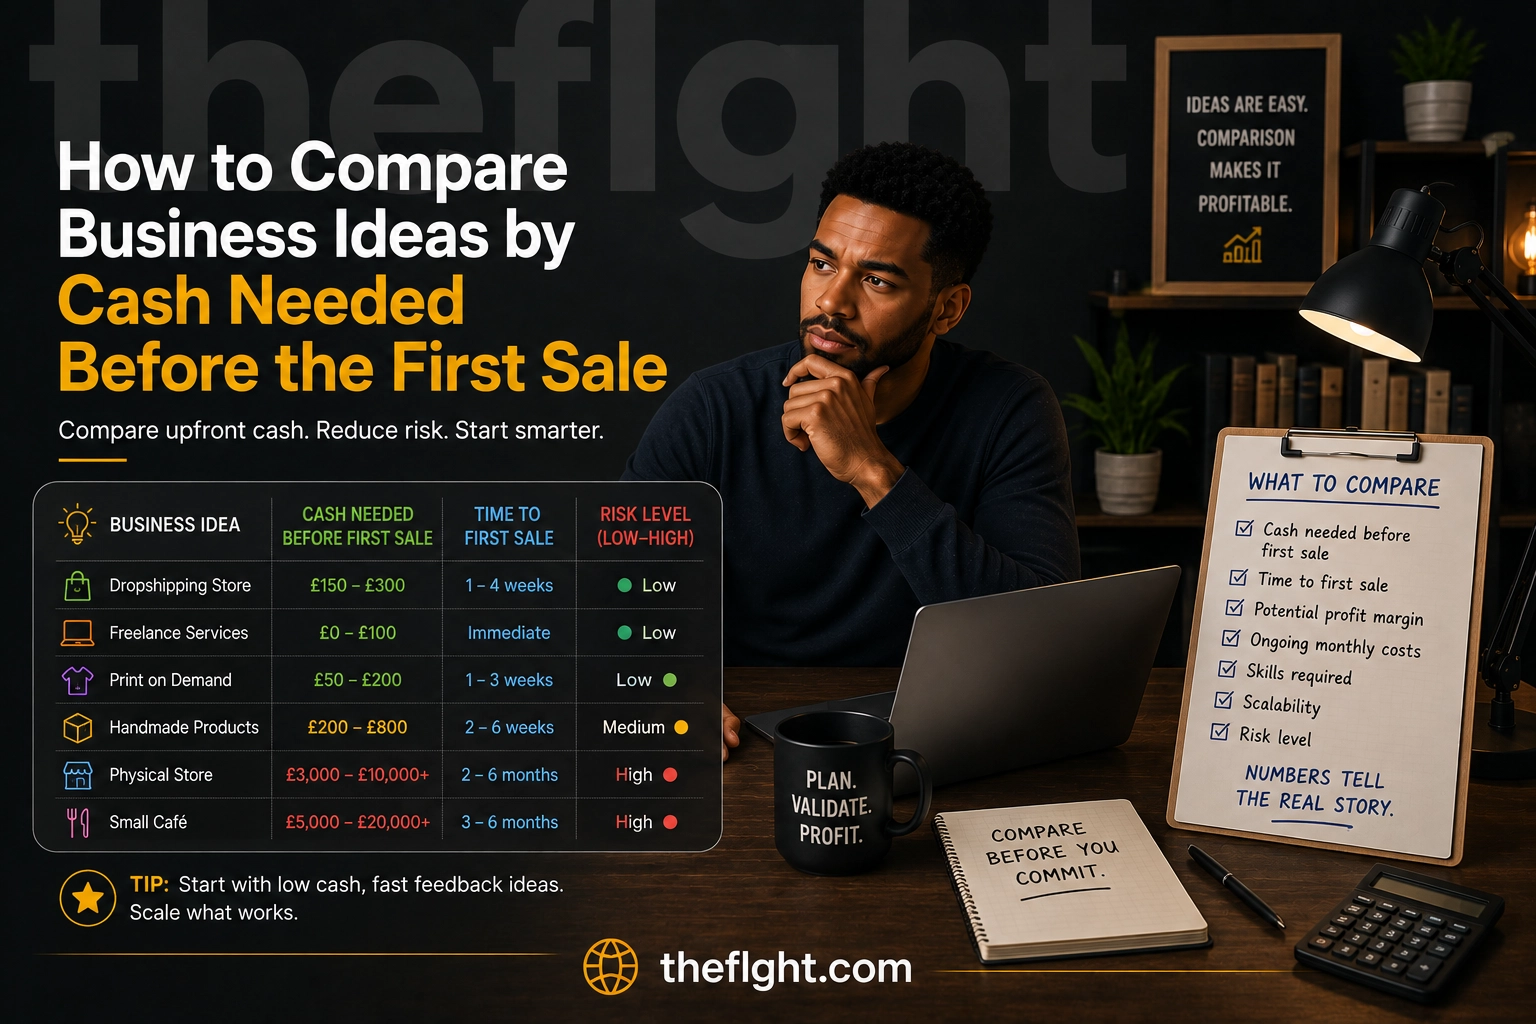
How to Compare Business Ideas by Cash Needed Before the First Sale
Short answer: Compare ideas by the largest cumulative cash deficit reached before customer money clears your account, not by a list of total startup costs. Map every payment and receipt in date order, include one failed or delayed sale, and keep personal living cash separate.
Prefer the idea whose peak exposure you can fund twice without borrowing against an optimistic forecast, unless the higher-exposure option has substantially stronger paid demand.
Two ideas can each “cost £5,000 to start” while creating completely different risk. One may spend £5,000 on resaleable equipment after signing a customer. The other may consume it on rent, promotion and stock months before anyone buys.
Totals hide timing, reversibility and what happens when the first sale is late. A comparison becomes useful only when every idea reaches the same milestone: cash received for a completed, compliant sale.
Use the Peak-Cash Exposure Map
The Peak-Cash Exposure Map records cash at five events. Start with a balance of zero for each idea, subtract each required payment and add customer cash only when it is actually available.
| Event | Include | Do not assume |
| Permission | Registration, licences, required checks, insurance and professional advice | Small scale creates an exemption |
| Proof | General attention will convert | |
| Commitment | Deposits received and costs triggered by the order | Every deposit is immediately spendable |
| Delivery | The first attempt will be defect-free | |
| Cleared payment | Final receipt after the payment period and deductions | An invoice equals cash |
The lowest cumulative balance is the idea's peak cash exposure. Add a separate contingency for one realistic failure, such as a refund, replacement or 30-day payment delay.
My view is that you should compare the first completed sale before comparing three-year potential. A founder who cannot fund the first honest transaction does not yet own the long-term opportunity.
Put costs on dates, not in categories alone
A category such as “stock £1,500” does not show whether stock is bought six weeks before launch or funded by a confirmed order. Put an expected date beside every amount. Use the earliest plausible payment date and the latest plausible receipt date.
For each idea, answer:
- What must be paid before you can ask for money?
- Which costs begin only after a customer commits?
- When can the customer cancel or request a refund?
- How long after delivery does usable cash arrive?
- Which payment repeats before the next sale?
An idea with a customer deposit can have a lower exposure than a nominally cheap service whose insurance, travel and equipment all precede booking. The label “service” or “product” does not settle the cash question.
Consumer, contract and payment rules vary by jurisdiction. Confirm how deposits, cancellations, refunds and customer funds must be handled with a qualified local professional before using them in your cash plan.
Separate consumed, recoverable and reusable spending
All cash leaving the account affects exposure, but not every cost creates the same downside.
| Spending type | Example | Value after a failed test |
| Consumed | Travel, advertising already run or professional time used | Usually none |
| Recoverable | Cash may return after delay and deductions | |
| Reusable | Suitable equipment or durable samples | Useful only if another sale or buyer exists |
| Committed | Lease, finance term or supplier order that cannot be cancelled | Future cash outflow remains |
Do not subtract an estimated resale value from exposure. Show the purchase cash first, then list conservative recovery separately with the likely time to sell. Resale is a downside option, not money available on the day you need it.
Reusable spending is not automatically better. Equipment built for a narrow idea may be economically worthless even if it still works. Ask what an unrelated buyer would pay, not what it cost you.
Compare at the same standard of proof
Founders often make the preferred idea look cheaper by giving it weaker evidence requirements. They budget a professional sample for one idea and assume a sketch is enough for the other. Define the same milestone: for example, one stranger pays the intended price and receives the minimum credible result.
Also apply the same cost for your time. Time is not part of peak cash exposure unless you pay someone, but it affects whether an idea is attractive. Report it beside the cash figure:
- Peak cash exposure before cleared payment
- Founder hours before cleared payment
- Cash contribution from the first sale
- Remaining commitments if the idea stops
An idea that needs £300 and 120 unpaid hours may be harder to fund than one needing £1,200 and 15 hours, depending on your job and living costs.
Worked example: Jade's bicycle business options
Jade is comparing a mobile bicycle repair service with buying and refurbishing one used bicycle for resale. Both target local commuters, but their cash paths differ.
For repair, she needs £760 of suitable tools, £70 of targeted outreach and £85 of parts for the first booked job. Travel costs £25. She charges £220 after completion.
| Repair event | Cash movement | Cumulative balance |
| Buy tools | negative £760 | negative £760 |
| Run outreach | negative £830 | |
| Buy parts | negative £85 | negative £915 |
| Travel and complete job | negative £940 | |
| Receive payment | positive £220 | negative £720 |
Peak cash exposure is £940. First-sale cash contribution after parts and travel is £220 minus £85 minus £25 = £110, but the reusable tools have not been recovered.
For resale, Jade pays £140 for a used bicycle, £95 for parts, £45 for an independent safety check and £20 for collection and listing activity. She sells it for £480, with £35 of payment and delivery costs deducted at sale.
| Resale event | Cash movement | Cumulative balance |
| Buy bicycle | negative £140 | negative £140 |
| Buy parts | negative £235 | |
| Safety check and listing | negative £65 | negative £300 |
| Sale clears after costs | positive £445 | positive £145 |
Peak cash exposure is £300, and first-sale cash contribution is £145. The stock-led idea needs less cash to complete this first transaction than the equipment-led service. That is the interesting result.
It does not prove resale is the better business.
Jade must test sales time, defect risk, consumer obligations, availability of suitable bicycles and her own labour. It proves that generic claims about services needing less cash can be wrong when equipment precedes demand.
These are illustrative quotes for Jade's comparison, not market benchmarks. Repair, product-safety, consumer and trading requirements must be checked for her location and activity.
Add a failed-sale scenario
Repeat each map with one bad outcome. For repair, the customer might cancel after non-returnable parts arrive. For resale, the bicycle might need an additional £90 repair or take eight weeks to sell.
Record the new peak and the commitments that continue. Do not simply add ten per cent to every cost. Name a mechanism that could fail and price it. This produces a more useful contingency than an arbitrary cushion.
Then ask whether you can fund the exposure twice. This is a conservative working rule, not a financial standard. Its purpose is to prevent the first delay from forcing you to abandon an otherwise sound test or use money reserved for rent and food.
Complete the comparison in five days
Choose no more than three ideas. On day one, define the same first-sale milestone for each. Over the next two days, obtain current written quotes and realistic customer payment terms.
Finish in this order:
- Plot every pre-sale payment and receipt by date.
- Identify the lowest cumulative balance.
- Add founder hours and post-sale commitments beside the cash figure.
- Run one named delay, cancellation or correction scenario.
- Reject any idea whose exposure would invade essential personal cash.
Use the map to decide which idea you can test safely now. Higher long-term potential can remain on the list, but it does not make missing cash disappear.
Frequently asked questions
Should I include tax in a first-sale cash comparison?
Yes, include any tax payment that the first transaction or setup spending creates within the period you are comparing. Keep amounts collected for an authority separate from contribution, and place expected payments on their actual dates rather than applying one guessed percentage to every idea.
Recoverable taxes, registration status and profit-based liabilities can make two apparently similar cash paths differ. Use current records and official guidance for your structure. Tax rules vary by country and activity, so obtain a calculation from a qualified local accountant when the amount or registration decision could change which idea is affordable.
Should I include my personal living costs in the map?
Keep them in a separate personal runway calculation, then test whether business exposure reduces that runway. Mixing the figures hides whether the idea works commercially, but ignoring living costs can force a premature stop. Record essential monthly spending, reliable outside income and the cash that must remain untouched.
Do not classify your rent or food as business startup costs. Instead, set a boundary the business may not cross. If the idea requires full-time unpaid work, the personal runway is part of feasibility even though it is not a business expense. Tax and benefits consequences should be checked locally.
How do I compare a subscription with a one-off sale?
Compare them through the cash required before the first cleared payment and the time needed to recover acquisition and setup. For a subscription, include onboarding, any free period, billing delay, cancellation and the cash cost of serving the customer before renewal.
Do not multiply the monthly fee by a year unless a binding term and collection evidence support it. For a one-off sale, include the full delivery cost and payment date. The subscription may have lower first-sale contribution but stronger recovery through repeats. Test a cancellation case and compare the lowest cumulative cash point, not headline contract value.
What if I can sell equipment or stock if the idea fails?
Show conservative recovery separately and delay it to the likely sale date. Deduct fees, transport, repairs and the discount needed for a reasonably quick sale. Do not reduce the original peak exposure because you cannot pay an earlier bill with later resale proceeds.
Also distinguish liquid stock from specialised items with few buyers. Model zero recovery as a downside case. If the idea is affordable only because you expect to resell near the purchase price, your margin of safety is thin. Tax, title and finance restrictions may affect disposal, so check the relevant terms and local advice.
How many customer sales should I include in the comparison?
Start with one completed and paid sale because it exposes the minimum cash path consistently across ideas. Then extend the map to the first ten sales or one normal operating month to reveal replenishment and payment-cycle problems. A first sale can look affordable while the second requires stock before the first invoice clears.
Keep the evidence levels equal for each idea. The exception is a model that cannot operate at one-unit scale, such as an event or batch with a genuine minimum. Use its smallest lawful, credible transaction and compare that larger commitment openly rather than inventing a one-sale version.
How do I compare ideas that reach the first sale at different speeds?
Compare both the deepest cash deficit and how long your money remains committed before usable payment arrives. An idea needing £500 for ten days creates a different constraint from one needing £500 for four months, especially when you have living costs or another test to fund.
Put calendar dates on each event and mark the day the balance first recovers. Do not assume the faster sale is better if its contribution is weak or the result cannot repeat. The exception is an urgent cash limit, where recovery time can rule out an otherwise attractive idea because you cannot survive long enough to prove it.
Comments (0)